Eway Bill Limit, Rules and Validity: Thresholds, Exemptions and State-Wise Limits
Do You Need an E-Way Bill? Quick Check
Use these four checks before relying only on the ₹50,000 figure:
- Check the consignment value. If it exceeds ₹50,000, an E-Way Bill is generally required unless a specific exemption applies.
- Check the type of movement. Interstate job work and certain handicraft movements can require an E-Way Bill even below ₹50,000.
- Check the state rule. For intra-state movement, the threshold or exemption may differ under the relevant state notification.
- Check for an exemption. Rule 138(14) covers specific goods and movements where an E-Way Bill is not required.
If any of these conditions apply, do not rely on the ₹50,000 figure alone.
The eway bill limit is only the first check. Certain goods or movements may require an E-Way Bill regardless of value, while others may be exempt. We explain these cases and the applicable state-wise limits below.
This is an independent informational guide and is not affiliated with GSTN, NIC or CBIC. For generation or management of an E-Way Bill, use the official E-Way Bill portal or see our E-Way Bill Login guide.
The General ₹50,000 E-Way Bill Threshold
Rule 138 of the CGST Rules, 2017 provides the general ₹50,000 test. When a registered person causes the movement of goods and the consignment value exceeds ₹50,000, an E-Way Bill is generally required before the movement begins.
Who is responsible depends on the transaction and who causes the movement. This may be the registered consignor, the consignee or, in relevant cases, the transporter carrying the goods. The e-way bill limit 50000 applies to the consignment itself. It is not linked to annual turnover or the total number of invoices a business issues.
Another important distinction is the wording “exceeding ₹50,000.” A consignment valued at exactly ₹50,000 does not cross the general threshold. This national eway bill limit comes from Rule 138 of the CGST Rules, 2017. CBIC rules also allow state-specific provisions for certain intrastate movements, discussed later on this page.
How Consignment Value Is Calculated
The consignment value for e-way bill purposes is based on the value determined under Section 15 and declared in the relevant invoice, bill of supply or delivery challan. It includes the applicable CGST, SGST, UTGST or IGST, along with any cess charged on the document.
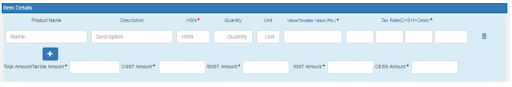
Where the same invoice contains both taxable and exempt goods, the value of the exempt supply is excluded when determining the consignment value.
| Component | Included? |
|---|---|
| Taxable value of goods | Yes |
| CGST / SGST / UTGST / IGST | Yes |
| Cess, where applicable | Yes |
| Exempt goods on the same invoice | No |
Worked example: Suppose taxable goods are worth ₹44,000 and 18% IGST adds ₹7,920. The same invoice also contains ₹5,000 of exempt goods. The relevant consignment value is ₹44,000 + ₹7,920 = ₹51,920. It therefore exceeds the general ₹50,000 threshold. For multiple invoices, separate E-Way Bills are generally generated for each invoice rather than combining several invoices into a single E-Way Bill.
Interstate vs Intrastate E-Way Bill Rules
A common mistake is to treat every eway bill limit as identical. For interstate movement, the general eway bill threshold limit is ₹50,000 under the central rules, subject to specific exceptions. For movement within a state, the applicable threshold or exemption can depend on that state’s notifications.
| Interstate | Intrastate | |
|---|---|---|
| General threshold | More than ₹50,000 | Depends on the state notification |
| Rule source | Central GST rules | State notifications |
| Uniform across India? | Generally yes | No |
| Can special conditions apply? | Yes | Yes, depending on the state |
So, the general eway bill limit for inter state movement remains ₹50,000 whether goods cross from Gujarat to Rajasthan or Kerala to Karnataka, unless a specific rule requires an E-Way Bill irrespective of value.
E-Way Bill Limit for Intra-State Movement
The eway bill limit for intra state movement is not always the same across India. States may issue their own notifications covering thresholds, exemptions or specified categories of goods moving within the state.
Some notifications may apply only to notified goods or particular types of intrastate movement. Intra-city movement should therefore not automatically be treated as exempt unless the relevant state notification specifically provides for it.
Before moving goods within a state, check the latest applicable state notification rather than relying only on the general ₹50,000 figure. The state-wise table later on this page should be used as a practical reference, while the notification remains the primary source.
State-Wise E-Way Bill Threshold
The eway bill threshold state wise can differ for intra-state movement because states may issue their own notifications, exemptions or special conditions. So, if someone asks, “Is the eway bill limit ₹1,00,000?”, the answer is no, not uniformly across India. A ₹1,00,000 limit applies only where the relevant state notification provides for it.
Last verified: 7/10/2026
Verification note: State-level thresholds and exemptions can change through local notifications. Each figure below should be matched to the latest notification published by the relevant state tax or commercial tax department before it is treated as current.
| State / UT | Reported intra-state threshold | Condition / scope | Source / date |
|---|---|---|---|
| Delhi | ₹1,00,000 | Intra-state movement originating and terminating within Delhi, subject to the notification conditions | Notification No. 3/2018, 15 June 2018, |
| Maharashtra | Current threshold: Verify latest state notification | Scope may depend on the applicable state notification and goods involved | |
| Tamil Nadu | Current threshold: Verify latest state notification | Confirm current intra-state scope before publication | |
| Punjab | Current threshold: Verify latest state notification | Confirm current intra-state scope before publication | |
| Rajasthan | State-specific | Check whether any exemption or special rule applies to intra-city or other local movement | |
| Bihar | Current threshold: Verify latest state notification | Confirm current intra-state threshold and exceptions | |
| West Bengal | State-specific | Check threshold, notified goods and current exemptions | |
| Other states / UTs | Check current notification | Do not assume ₹50,000 or ₹1,00,000 without verification | State commercial tax department / state tax portal |
Because state rules can be amended, businesses should check the latest notification from the relevant state commercial tax department or state tax portal, especially for local or intra-city movement. For recent changes, see Latest E-Way Bill Updates.
Primary source: Rule 138 of the CGST Rules and official E-Way Bill System guidance. Regulatory details were checked against official sources on DATE.
When an E-Way Bill Is Required Below the Limit
Warning: Being below the eway bill limit does not always mean an E-Way Bill is unnecessary.
There are specific cases where the value threshold does not apply:
- Interstate job work: If a principal sends goods to a job worker in another state or Union Territory, an E-Way Bill is required irrespective of consignment value. It may be generated by the principal or by the job worker if registered. This is the key rule for e way bill for job work below 50000.
- Handicraft goods: Certain interstate movements of handicraft goods by persons exempt from registration also require an E-Way Bill irrespective of value. Notification 56/2018-CT is relevant to the definition of handicraft goods.
- State-notified goods: A state may prescribe special requirements for particular notified goods or movements. Always check the latest applicable state notification.
E-Way Bill Exemptions and When One Isn’t Needed
An Eway Bill may not be required even when goods exceed the normal value threshold. Rule 138(14) lists specific exemptions, while other cases depend on how and why the goods are moved.
E-Way Bill Exemption List (Summary)
Rule 138(14) contains the official eway bill exemption list. Rather than reproducing every item, the table below groups some of the main categories. Always check the rule and latest notifications for the exact conditions.
| Category | What it generally covers |
|---|---|
| Goods listed in the Rule 138 Annexure | Specified goods expressly excluded from the E-Way Bill requirement |
| Non-motorised transport | Goods carried by a non-motorised conveyance |
| Customs-controlled movement | Certain goods moved under customs bond, customs supervision or customs seal |
| Specified non-taxable or exempt categories | Certain notified goods, including specified exempt supply categories |
| Government, defence and transit cases | Certain defence movements, transit cargo and other specifically listed situations |
Official reference: Rule 138(14) of the CGST Rules, CBIC
Situations Where an E-Way Bill Is Not Required
| Situation | E-Way Bill position |
|---|---|
| Goods moved only by non-motorised conveyance | eway bill not required under Rule 138(14), subject to the applicable conditions |
| Goods moved by railways | Transport by rail is not, by itself, an exemption; apply the normal E-Way Bill rules and relevant transport-document requirements |
| Goods moved by air | Air transport is not, by itself, an exemption; normal applicability rules still need to be checked |
| Goods moved by vessel | Vessel transport is not, by itself, an exemption; normal applicability rules still need to be checked |
E-Way Bill Validity and Distance Rules
The eway bill validity is based on the distance the goods are expected to travel. Since Notification 94/2020-CT, normal cargo gets one day of validity for every 200 km or part thereof. The older 100 km-per-day rule is outdated.
For normal cargo, the current rule allows one day for every 200 km or part thereof. Under Rule 138, the relevant date is the date on which the E-Way Bill is generated, and each day of validity is counted according to the midnight rule prescribed there. The older 100 km-per-day standard is no longer current.
| Distance for normal cargo | Validity |
|---|---|
| Up to 200 km | 1 day |
| 201–400 km | 2 days |
| 401–600 km | 3 days |
| Every further 200 km or part thereof | 1 additional day |
Worked example: For eway bill validity for 200 km, an E-Way Bill generated on 5 March is generally valid until midnight at the end of 6 March. A 450 km journey gets three days of validity, so it would run until midnight at the end of 8 March. If the journey is delayed, see Update or Manage an Existing E-Way Bill.
Over-Dimensional Cargo and Shipments with a Sea Leg
The over dimensional cargo eway bill validity is one day for every 20 km or part thereof. Over dimensional cargo means a single indivisible load that exceeds the dimensional limits under Rule 93 of the Central Motor Vehicle Rules, 1989. The same 20 km-per-day rule also applies to a multimodal shipment by ship where at least one leg involves transport by ship.
Document-Age and Extension Limits
Two separate time restrictions apply in addition to the normal distance-based validity rules.
Document age: Under the eway bill 180 days rule, an E-Way Bill cannot be generated where the invoice or other underlying document is dated more than 180 days before the E-Way Bill generation date. GSTN announced this validation in its December 2024 advisory, with effect from 1 January 2025.
Extension: The eway bill extension rules allow validity to be extended in exceptional situations, such as a vehicle breakdown, accident, natural calamity, law-and-order issue or transshipment delay. If a shipment is delayed for an eligible reason, you can request an extension within eight hours before the E-Way Bill expires or during the eight hours following expiry.
A further system restriction prevents an extension from taking the E-Way Bill beyond 360 days from its original generation date. For the process, see Extend an E-Way Bill on the Portal.
Exceptions That Change the Usual Answer
The e way bill limit does not tell the whole story in these three situations:
- Per-vehicle aggregation: Several consignments travelling in the same vehicle do not automatically become subject to the ₹50,000 limit simply because their combined value exceeds ₹50,000. The official E-Way Bill FAQ states that Rule 138(7), which deals with this aggregate-value situation, is to take effect only when separately notified. Until then, consignments below ₹50,000 are not brought within the requirement solely because their combined vehicle value crosses ₹50,000.
- Short-distance Part B proviso: For movement of less than 50 km within the same state or Union Territory from the consignor’s place to the transporter’s place for further transportation, the conveyance details in Part B may not be required at that stage.
- Voluntary generation: A registered person or, where applicable, a transporter may choose to generate an E-Way Bill even when the consignment value is ₹50,000 or less.
Three Common E-Way Bill Limit Mistakes
- Treating ₹50,000 as the same threshold for every intra-state movement.
- Looking only at the taxable value and forgetting applicable GST and cess while calculating consignment value.
- Assuming that every consignment below ₹50,000 is exempt without checking job work, handicraft or state-specific rules.
Eway Bill Limit and Validity FAQs
What is the e-way bill limit in India?
The eway bill limit in India is generally ₹50,000 per consignment for interstate movement. For intra-state movement, the applicable threshold or exemption may depend on the notification issued by the relevant state.
Is the e-way bill limit of ₹50,000 including GST or not?
Yes. Consignment value includes applicable CGST, SGST, UTGST, IGST and cess shown on the document. Where one invoice contains taxable and exempt goods, the exempt portion is excluded while calculating the relevant consignment value.
Does the limit count one invoice or the whole vehicle?
Generally, a separate E-Way Bill is generated for each invoice. Multiple invoices cannot be combined into one E-Way Bill simply because they travel in the same vehicle.
When is an e-way bill required?
An E-Way Bill is generally required when goods cross the applicable value threshold, although certain movements, such as qualifying interstate job work, may require one regardless of value. See Generate an E-Way Bill for the process.
Is the e-way bill amount limit the same in every state?
No. The general central threshold applies to interstate movement, while states may prescribe different thresholds, exemptions or conditions for intra-state movement through their own notifications.
How long is an e-way bill valid, and can it be extended?
For normal cargo, validity is generally one day for every 200 km or part thereof. In eligible circumstances, an extension may be requested within 8 hours before or 8 hours after expiry, subject to the current 360-day system cap. See Extend an E-Way Bill on the Portal.
ewaybillinfo.com
Independent guides to E-Way Bill login, registration, generation, management, limits, penalties and latest updates. Always use the official government portal for account actions.
Guides
Official portals
© 2026 ewaybillinfo.com. All rights reserved.
Independent informational website. ewaybillinfo.com is not affiliated with, endorsed by, or operated by the Government of India, GSTN, NIC, CBIC, or the official E-Way Bill portal. Information on this site is provided for general guidance and may change as government rules, portal features, or procedures are updated. Always verify important details on the official government portal before taking action. We never ask for your E-Way Bill password, OTP, login credentials, or other sensitive account information.